
Most people's first question about a SACCO loan is simple: do I need guarantors, and how much can I actually borrow? The honest answer is that it depends entirely on one number, the gap between how much you want to borrow and how much you have saved. Everything else, guarantors, collateral, waiting periods, exists to close that gap. Once you understand that, the whole system stops feeling like a mystery.
The one rule that explains almost everything
Every SACCO loan in Kenya is built around the same core idea: your savings are your primary security. SACCOs typically lend a multiple of your savings, commonly three to five times what you have contributed, depending on the loan product. If your requested loan amount is equal to or less than your savings, you generally will not need a guarantor at all. The moment you ask for more than your savings can cover, that extra amount, the gap, has to be backed by something else: a guarantor, collateral, or in some cases loan insurance.
Understanding this one rule makes every SACCO's requirements page make a lot more sense.
What counts as savings, and how the multiplier works
Savings usually means your share capital plus your regular deposit contributions with that specific SACCO, not money sitting in an unrelated bank account. Most SACCOs require:
- Active membership, often for a minimum of 6 months before you qualify for larger loans
- Consistent monthly contributions, since a steady pattern matters more than one large deposit
- A minimum share capital balance to remain an active, voting member
The loan multiplier then determines your ceiling. If a SACCO uses a three times multiplier and you have saved KSh 100,000, you can typically borrow up to KSh 300,000 without needing to bring in a guarantor or collateral, since your own savings fully secure that amount.
When you do not need a guarantor
You can generally skip guarantors entirely in these situations:
- Self-guaranteed loans. If your loan amount is equal to or less than your savings, most SACCOs allow full self-guarantee. Some even offer this as a named product specifically for members who do not want to chase down guarantors.
- Collateral-backed loans. Pledging land, a title deed, a fully owned and comprehensively insured vehicle logbook, or a fixed deposit can replace the guarantor requirement, since the asset itself becomes the security.
- Certain loan categories. Some SACCOs waive guarantors entirely for specific products, such as asset financing loans, home loans, or equity release loans, because the item being financed or the deposit backing it already secures the loan.
When you do need a guarantor
If you want to borrow more than your savings can cover and you have no acceptable collateral to offer, guarantors become necessary. In this setup:
- Two to five fellow members typically pledge their own savings against your loan
- A guarantor cannot commit more than their own uncommitted savings can cover
- If you default, the SACCO can recover the outstanding balance from your guarantors' savings
This is why guarantors are usually people close to you within the SACCO, since they are taking on real financial exposure by backing your loan.
Using land or a title deed as collateral
Land is one of the most common alternatives to guarantors, especially for larger development or construction loans. Here is generally what is involved:
- A land search must be conducted and the official certificate submitted for the SACCO's credit committee to review.
- A professional valuation is required, usually by a valuer the SACCO itself approves, and the loan is based on current assessed value, not your original purchase price.
- The SACCO lends a percentage of that valuation, commonly around 40 to 60 percent for land outside major towns, and sometimes 60 to 80 percent for land in and around Nairobi, though this varies by SACCO.
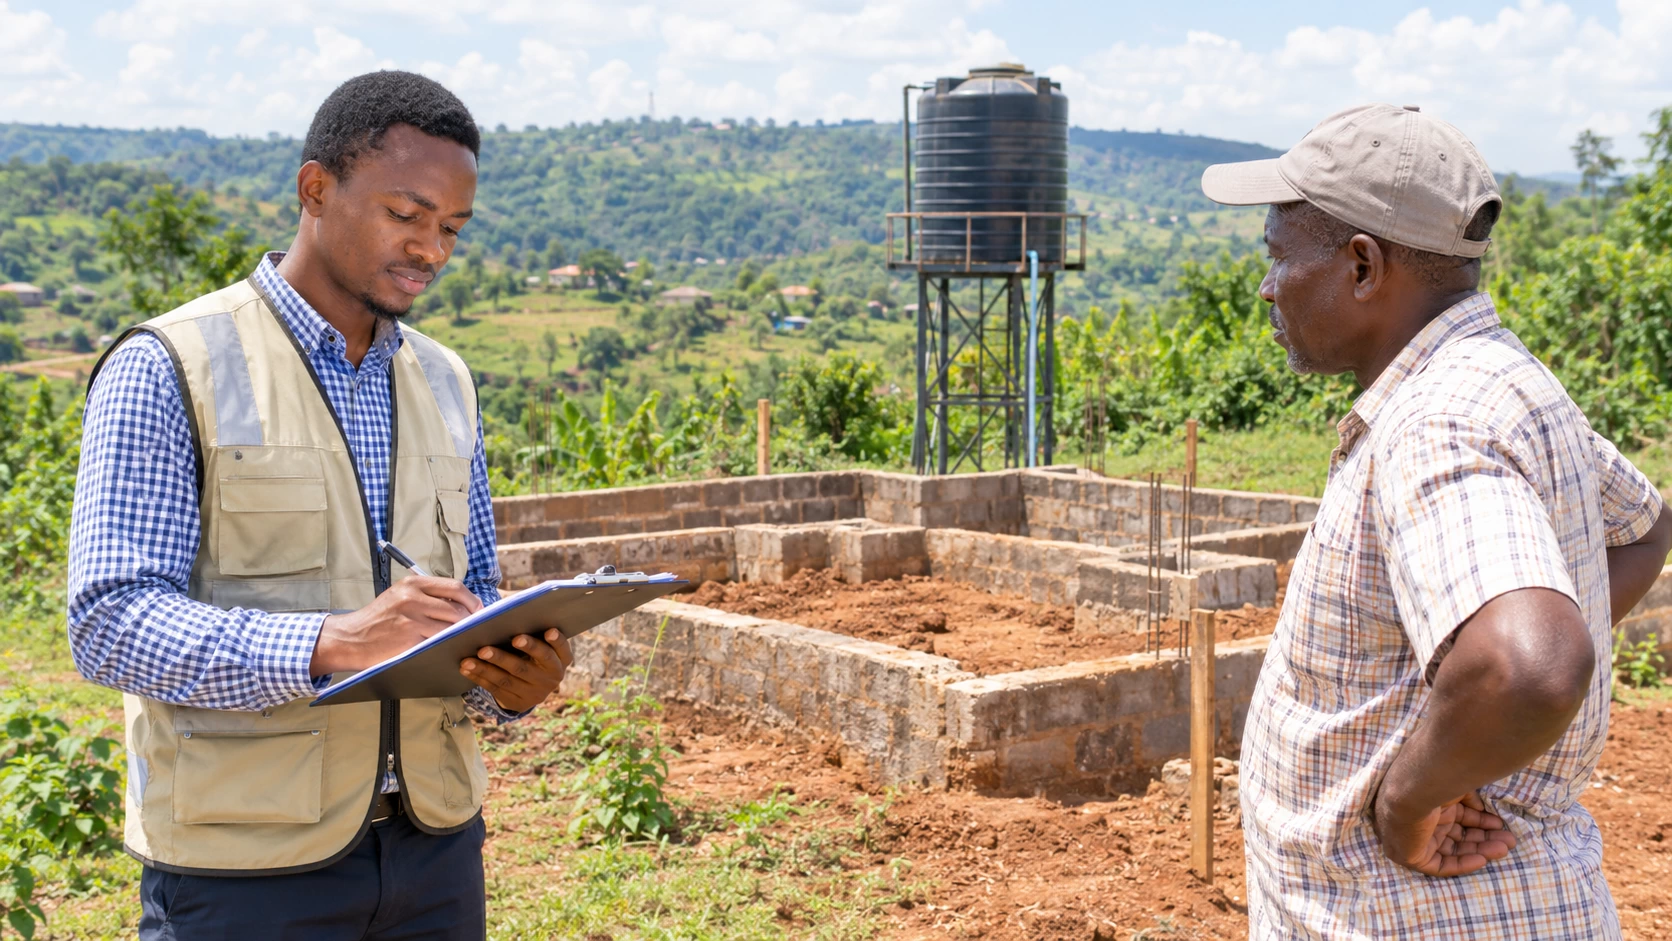
- Partial development helps but has limits. A foundation, a water tank, or other early-stage structures can lift a valuation slightly above bare land, but they carry far less weight than a completed or near-complete house.
- Some categories require additional consent, for example from the National Land Commission, depending on how the land is classified.
Can you get a loan with a title deed and no savings at all?
This is one of the most common misunderstandings. Collateral like a title deed strengthens how much you can borrow, but it does not replace the need to be an active, contributing member. Almost every SACCO requires:
- Registered membership and a minimum contribution history, even if modest, before a loan application is considered
- Some track record of saving, even a small monthly amount, to demonstrate financial discipline
In practice, someone with strong land collateral but zero savings history will usually need to join the SACCO, start contributing, and wait out the minimum membership period, often around 6 months, before a land-backed loan application will even be reviewed. The land makes the loan possible once you are eligible. It does not skip eligibility altogether.
A realistic example
Say a member joins a SACCO and starts saving KSh 2,000 a month. After 7 to 8 months, they have roughly KSh 14,000 to 16,000 saved, enough on its own for a loan of perhaps KSh 40,000 to 80,000 depending on the multiplier. If they also own a plot of land worth around KSh 800,000 to 1 million with a foundation and water tank in place, and that land is accepted as collateral at, say, 50 percent of assessed value, the land could support a loan in the range of KSh 400,000 to 500,000, far more than the savings alone would allow. The combination of modest, consistent savings plus solid collateral is what typically unlocks a meaningful loan amount, not either one on its own.
Documents you will generally need
- National ID and KRA PIN
- Proof of income, such as payslips, bank statements, or audited accounts if self-employed
- Land search certificate and valuation report, if using land as collateral
- Guarantor forms and ID copies, if using guarantors
- A clear statement of the loan's purpose, such as a sale agreement or a construction budget
The bottom line
A SACCO loan is not a single fixed process, it flexes based on what you bring to the table. Strong savings alone can get you a self-guaranteed loan with no guarantors needed. Strong collateral like land can extend how much you borrow well beyond your savings. What no SACCO skips is membership itself, you need to be an active, contributing member before any of these paths open up. If your situation involves land, partial construction, or limited savings, the most useful thing you can do is call your target SACCO branch directly and ask exactly what their multiplier, minimum membership period, and land collateral percentage are, since these details genuinely vary from one SACCO to the next.