
Ask five different people what a piece of land is worth and you will likely get five different numbers, the seller's asking price, the neighbor's guess, an agent's estimate, what you saw on a listing site, and what a bank thinks it is worth. Only one of these actually matters when it comes to loans, taxes, inheritance, or court disputes: a formal valuation done by a licensed professional. Here is exactly how that number gets calculated.
Why a proper valuation matters
A valuation report carries real legal and financial weight. Banks and SACCOs require one before accepting land as loan collateral. Courts rely on them in succession and inheritance disputes. The Kenya Revenue Authority and county governments use them for tax purposes. And if you are simply buying or selling, an independent valuation protects you from paying too much or accepting too little based on a seller's or agent's guess.
Only a valuer registered with the Valuers Registration Board (VRB) under the Valuers Act, Cap 532, or affiliated with the Institution of Surveyors of Kenya (ISK), can produce a report that banks, courts, and government bodies will actually accept. Always confirm registration before hiring anyone for this work.
The three main methods valuers actually use
Professional valuers in Kenya rely primarily on three recognized approaches, and which one applies depends on the type of land and the purpose of the valuation.
1. The Market Approach (Comparative Method)
This is the most widely used method for residential and most vacant land. The valuer identifies recent sales of genuinely comparable parcels in the same area, then adjusts for differences in size, shape, location, and access. If a similar half-acre plot two streets away sold for KSh 4 million six months ago, that sale becomes the benchmark, adjusted up or down based on how this specific parcel differs.
This method works well precisely because Kenya has no centralized public transaction database, so a valuer's skill in sourcing genuine, recent comparable sales, not just asking prices, is what separates a defensible valuation from a guess dressed up as one.
2. The Income Approach
Used for land or property that generates or could generate rental income, commercial plots, rental apartments, or income-producing agricultural land. The valuer estimates the income the property currently generates or could realistically generate, then works backward to a value using a capitalization rate appropriate to that type of property and area. A commercial plot in a strong retail corridor will typically command a different capitalization rate than similar land in a quieter suburb, which is part of why two seemingly similar plots can carry very different valuations.
3. The Cost Approach
Used less often for bare land, but relevant when a plot has existing structures or improvements. This method estimates what it would cost to replace the current improvements, then adds that to the land's own value, adjusting for depreciation on anything already built. It tends to matter most for specialized properties without many comparable sales to draw on.
A fourth method, the Residual Method, sometimes comes up for development land, working backward from an expected completed sale value minus construction costs and developer profit to arrive at what the raw land itself is worth. This method is inherently sensitive to its underlying assumptions, so it carries more built-in uncertainty than the other three.
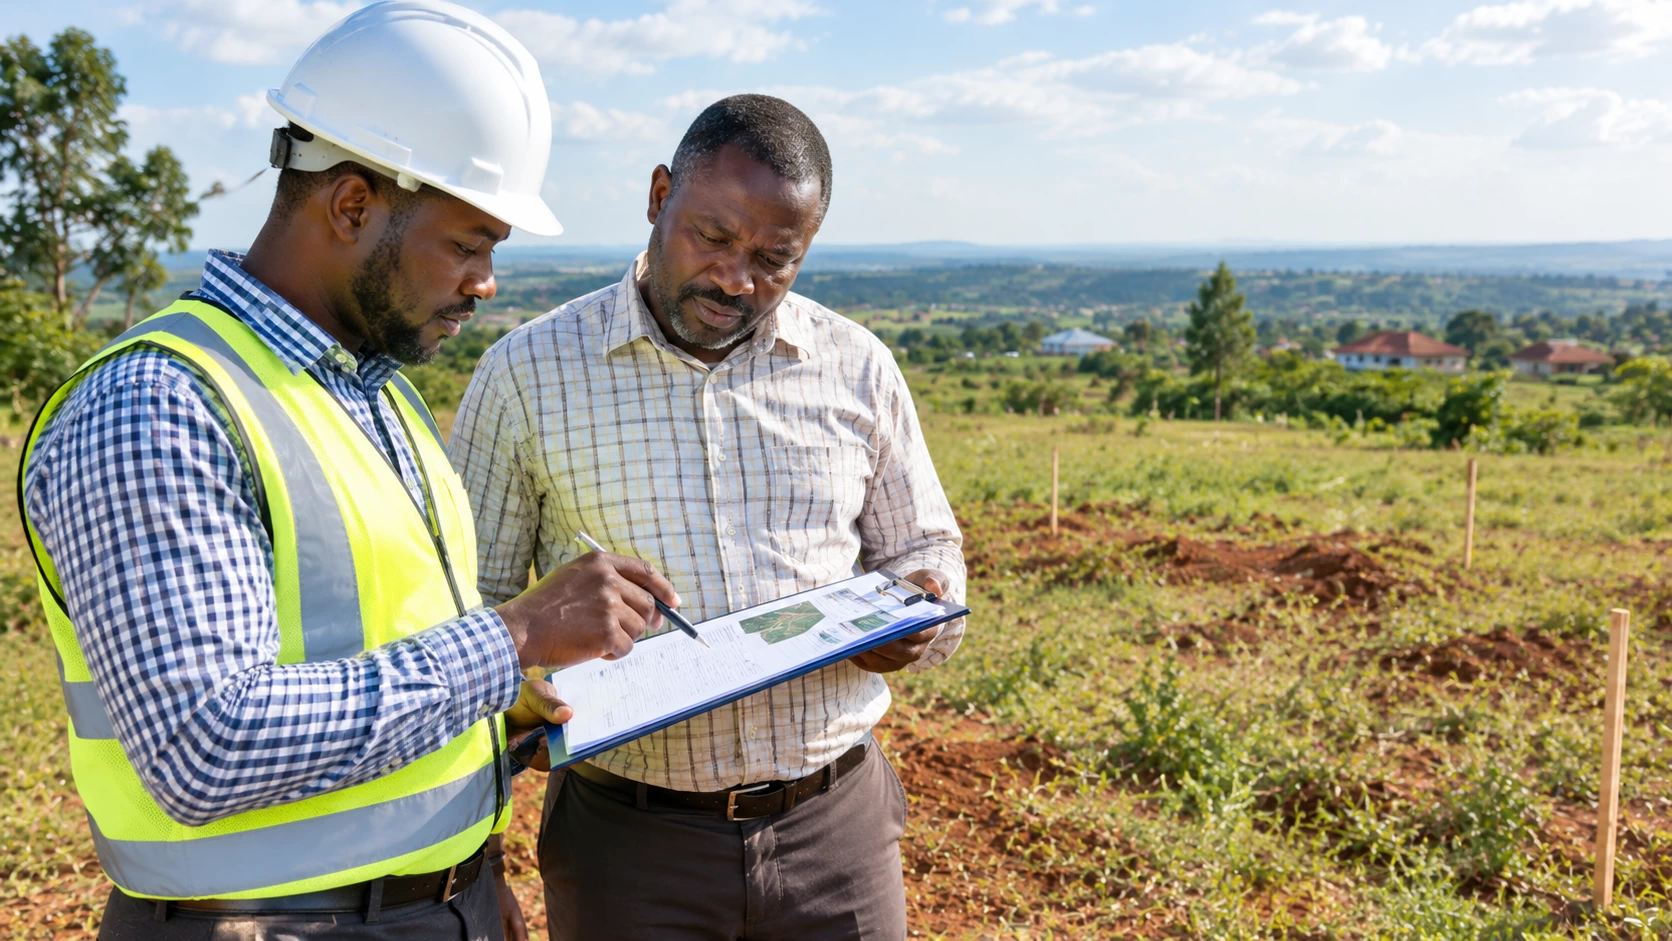
What actually moves the number up or down
- Location. Proximity to schools, hospitals, main roads, and commercial centers consistently drives value more than almost any other single factor.
- Size and shape. Larger, well-proportioned, easily accessible parcels typically value higher per unit than oddly shaped or landlocked ones.
- Tenure and remaining lease term. Most commercial and much residential land in Kenya sits on leasehold tenure, often a 99 year term. What actually matters for value is the remaining years left, not the original term. Once the unexpired term drops below roughly 40 to 45 years, banks generally will not accept it as mortgage security, which caps achievable value regardless of anything built on it.
- Zoning and planning compliance. Land used or developed outside its approved zoning, or lacking proper county approvals, sees its marketability and valuation reduced accordingly, no matter how good it looks on the ground.
- Title quality. A defective title, unresolved boundary dispute, or missing right of access can deter lenders entirely, or require costly indemnity insurance, both of which drag the value down.
- Infrastructure and future development potential. Areas earmarked for new roads, utilities, or planned growth corridors often see valuations rise ahead of the actual development, priced in based on expectation.
- Natural features. Rivers, hills, wetlands, or riparian reserves can either add character and value or restrict how the land can be used, depending on the specific feature and local regulation.
What a valuation actually costs
Fees scale with the property's value and complexity. As a general guide:
- Residential land and property valuations typically range from around KSh 15,000 to 60,000
- Larger or more complex valuations, including commercial land, can run higher, commonly cited in the KSh 50,000 to 100,000 range or more depending on size and purpose
Confirm the fee upfront and get it in writing before the valuer begins work, since complexity and travel can push the cost up.
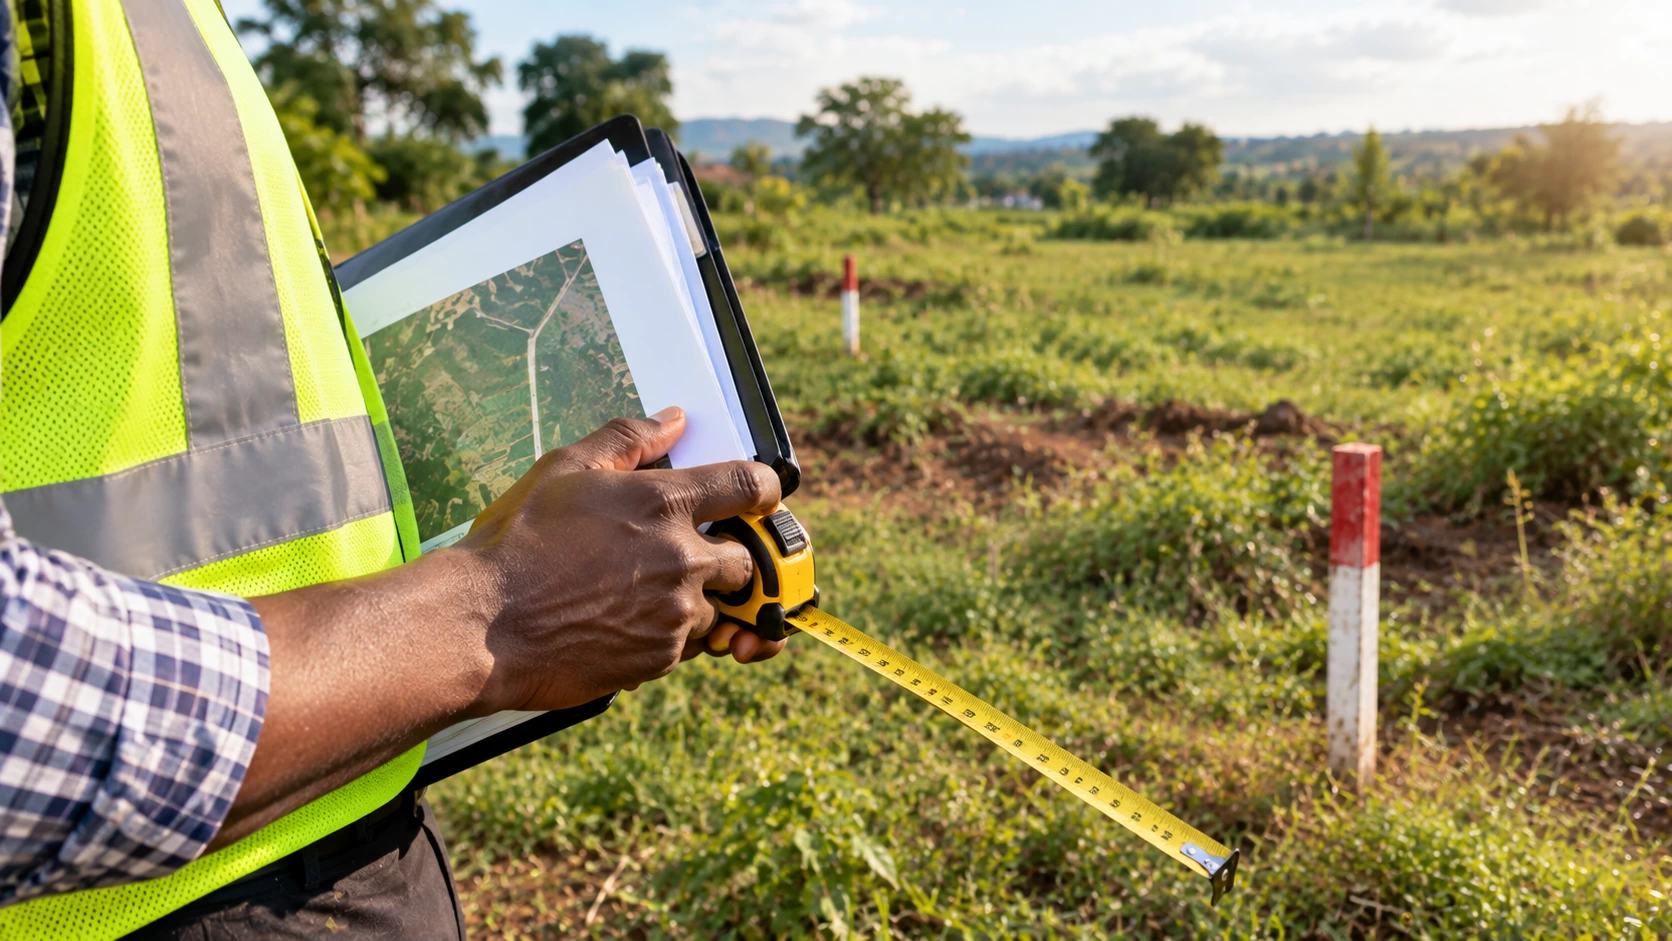
How to hire the right valuer
- Confirm registration with the Valuers Registration Board or membership with the Institution of Surveyors of Kenya before engaging anyone.
- Ask for their purpose-specific experience. A valuer experienced in bank collateral valuations is not automatically the best fit for a succession or inheritance valuation, and vice versa.
- Get a written scope and fee quote before work begins, covering exactly what the report will include and cover.
- Request the full written report, not just a verbal figure, since this document is what banks, courts, or the taxman will actually rely on.
- Cross check the report's method against what you have read here. A valuation with no comparable sales data, no stated method, and no explanation for its figure is a weak report regardless of who signed it.
The bottom line
Land value in Kenya is not whatever a seller decides to ask for it. It is a defensible number built from comparable sales, income potential, replacement cost, or a combination of these, adjusted for location, tenure, title quality, and zoning compliance. Whether you are buying, selling, using land as loan collateral, or settling an inheritance, a proper valuation from a VRB-registered professional protects you from both overpaying and underselling. It is a small cost against the size of the decision it informs.